 ASX: OSM · Orión Project
Minerals Hub / Applications & Industries / Semiconductors
Applications & Industries · Section 05 of 11
Semiconductors
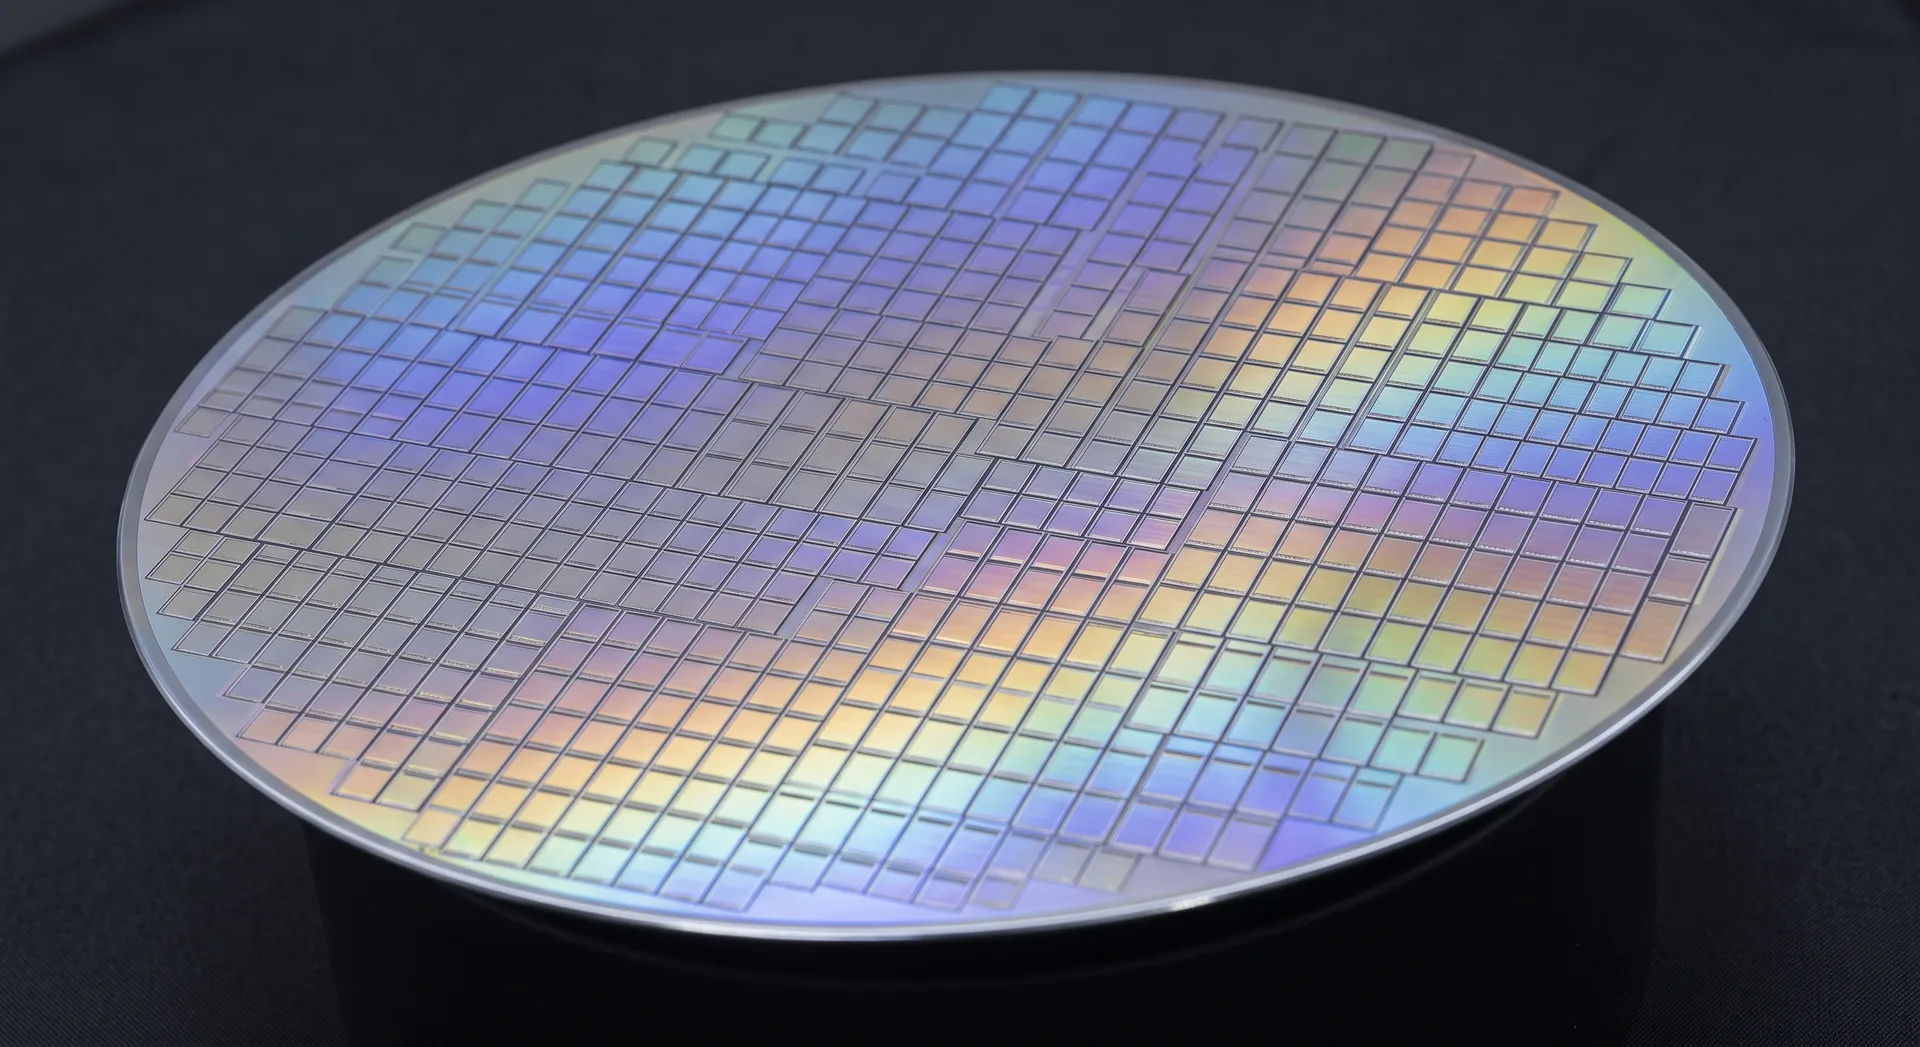
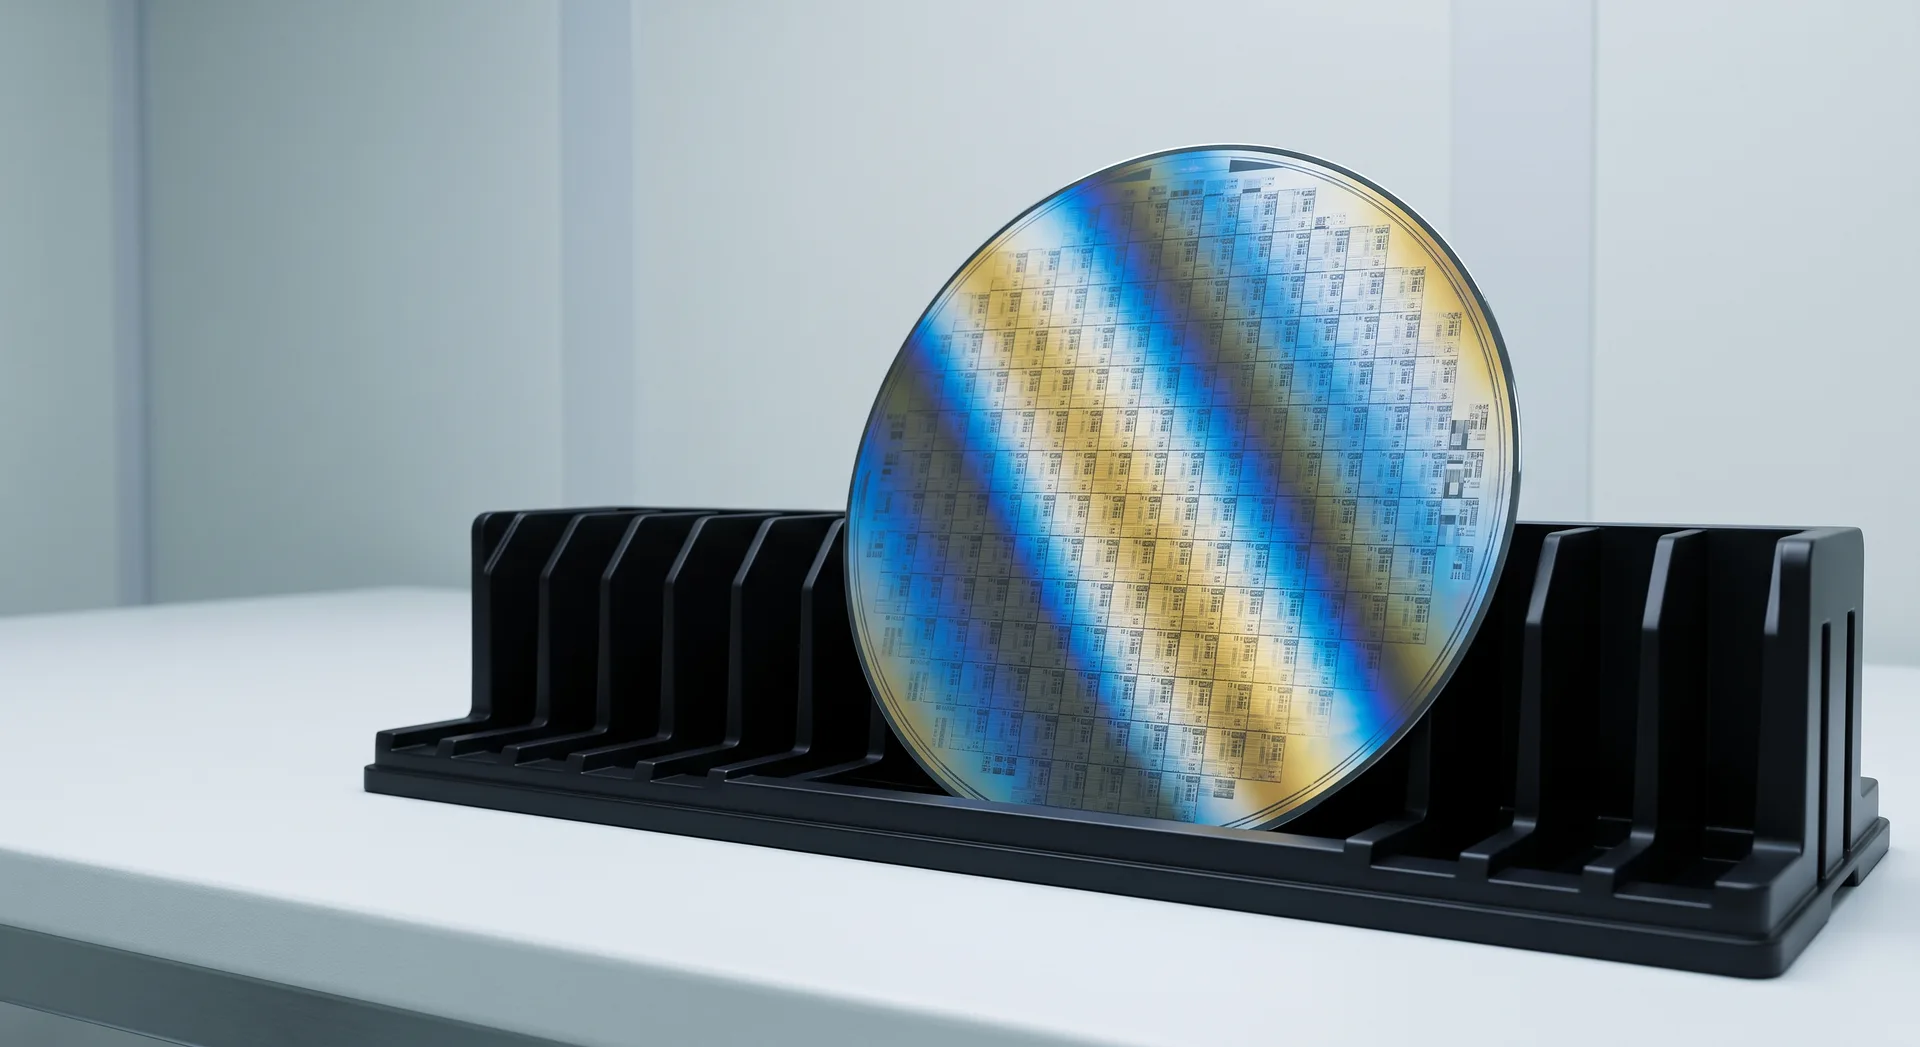
Purity, not tonnage, is what qualifies a mineral as a semiconductor input. Very little material by weight goes into a wafer, yet the specifications on that material are among the most demanding anywhere in industry — which is why a handful of deposits and refiners matter far out of proportion to what they ship. What follows concerns chipmaking as a buyer of mineral products, rather than as a technology in its own right.
High-purity quartz is the clearest link. It becomes the crucibles in which silicon ingots are pulled, and the fused silica used in furnace ware, photomask substrates and lithography optics. Hafnium supplies a second, less familiar one: hafnium oxide replaced silicon dioxide as the gate dielectric in advanced logic, and the hafnium in question is separated from zirconium that began as zircon. Rare earths contribute through cerium-based slurries used to polish wafers flat between process steps, and through dopants and specialty compounds used in smaller quantities. Titanium appears in metallisation and barrier layers within the device stack.
Each of those inputs runs from mineral to fab-qualified product through a purification step performed by very few companies — a stage more concentrated than mining, and the place a shortage would first appear. Semiconductor-grade specifications resist substitution, chip demand transmits into mineral demand with a considerable lag, and only some of these materials are genuinely consumed rather than recovered within the fab.
Silica/HPQ and Hafnium are the two resource pages that matter most for this subject, with Rare Earths behind the polishing and doping chain. Electronics covers the devices built from these chips, and Supply Chain Risk deals with the concentration this page keeps running into.